EU Midday Digest - 10 Nov 2026
AI-generated midday market digest from curated financial newsflow.
Fed's Waller signals December hike size hinges on today's CPI with 99% probability priced.
Asia-Pacific & European Session
Asia-Pacific equity markets advanced strongly, with the Nikkei 225 rising 2.87% to 60,460 in the 06:45 JST session and the Hang Seng gaining 0.44% to 24,557. European indices followed suit at the 11:27 CET open: Euro Stoxx 50 up 1.18% to 6,365, DAX up 1.27% to 26,600, and FTSE 100 up 0.44% to 10,831. Brent crude traded at 91.21, down 1.47% on the session as US-Iran diplomatic progress reduced the geopolitical risk premium. The dollar index held at 101.73 while gold retreated to 4,079 and bitcoin slipped to 74,193, both pressured by rising December Fed hike expectations. The divergence between resilient European equities and fading alternative assets reflects the market's focus on today's CPI as the pivotal catalyst for rate-path repricing.
Key Themes
- Fed Policy & CPI: Federal Reserve Governor Christopher Waller stated a December rate hike is warranted regardless of the October CPI print, but the magnitude depends on core inflation: 25 bps if it improves, 50 bps if core CPI m/m comes in at 0.3% or higher. He called September inflation "bad" and highlighted broad-based price pressures. Fed funds futures now price a 99% probability of a December hike, with an 84% chance of 25 bps. Morgan Stanley and Bank of America lean toward a softer 0.2% headline and 0.19% core, citing shelter and services normalization, but BofA notes only an "indisputably soft 0.1% reading could affect the calculus." InvestingLive notes the core CPI forecast distribution is skewed upside: 66% at 0.2% consensus but 31% at 0.3%. Year-over-year figures will not be published due to last year's government shutdown, concentrating all reaction on month-over-month measures. Source: InvestingLive, Bloomberg, CNBC.
- European Central Banks Divergence: Sweden's Riksbank minutes show officials see "a persistent risk of higher inflationary pressure over the months ahead" and believe "a further increase in borrowing costs will likely be needed," signaling a hiking cycle rather than a one-off. ECB Chief Economist Philip Lane said the ECB "should raise borrowing costs again at its next meeting if the data don't shift," making a December hike the default path. However, Governing Council member Martins Kazaks warned rate-hike judgments are getting "more nuanced" as the ECB weighs inflation against growth fallout, implying the terminal rate may be near. Critically, Lane drew a hard line on France: the ECB "shouldn't adjust the run-off of its bond holdings or deploy its crisis tool to help France with its budget problems," removing a tail-risk hedge for French sovereign spreads. Source: Bloomberg Economics.
- Oil & Geopolitics: Brent crude fell below $90 a barrel for the first time since August (market data shows 91.21 at 11:31 CET), deepening a selloff as traders increased bets on a Middle East resolution. Bloomberg attributes the drop to diplomatic efforts by the US and Iran pushing Brent lower, while CNBC reports Trump declared Iran "militarily effectively over" and predicted the conflict would end "fairly soon." The risk premium compression could ease inflationary pressures and weigh on energy equities, but markets should treat political rhetoric as unconfirmed until Pentagon or State Department validation. Source: Bloomberg Markets, FT, CNBC.
- AI/Tech Governance & Valuation Stress: Nvidia shares fell after the board opened an investigation into an alleged Chinese spy scandal following CEO Jensen Huang's admitted affair, with the FT framing his tenure as a governance issue for the market's most-watched chipmaker. Anthropic's draft IPO prospectus targeting up to $64.4 billion (Reuters) or $69.3 billion (MarketWatch, before retraction) would rank among the largest tech listings ever, testing appetite for unprofitable frontier AI models. The rapid retraction suggests internal disagreement or market-timing concerns. SoftBank reported its first quarterly loss in nearly two years due to a writedown on US data centre projects from "evolving requirements," while Bloom Energy slumped 26.6% in October on Oracle and AI sell-off developments. Source: FT, Investing.com, MarketWatch, Nasdaq.
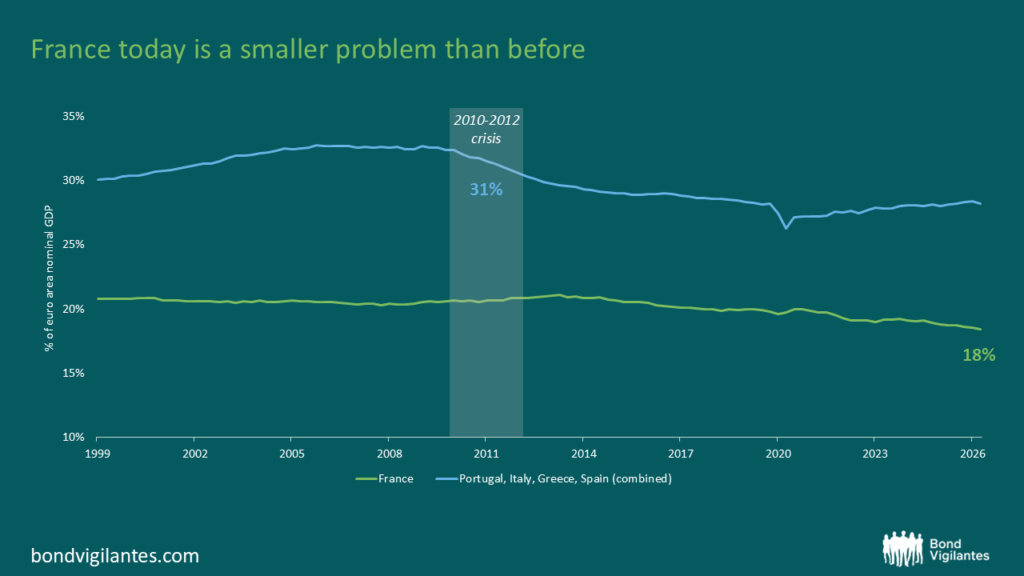
- France Fiscal Risk: The ECB's refusal to backstop France's budget problems — "must be fixed in Paris" per Lane — removes implicit TPI/PEPP support for French OATs. Bond Vigilantes notes the current budget finds €54bn of savings but only reduces the deficit from 5.4% to 5.0% of GDP on growth assumptions France's fiscal watchdog considers optimistic. Holding debt steady at today's yields would require a primary surplus above 2% of GDP, exceeding France's best five-year average since 1995. Fitch warns a "rather painful solution" may be needed, with FROGS (French Restructuring Of Government Securities) risk looming ahead of the 2027 presidential election. Source: Bloomberg Economics, Bond Vigilantes.
13F Filings
Two major funds filed 2026Q3 13Fs since November 9: Baillie Gifford & Co (US$ 106bn, 278 positions) and Acadian Asset Management (US$ 86bn, 1,982 positions). Eleven of 115 tracked funds have now filed; holdings reflect quarter-end positions, not current trading. Cross-fund consensus shows net buying in CTAS (2 new, 3 added), APO (1 new, 3 added), PAYX (0 new, 4 added), and ADIG (3 new, 0 added). Net selling concentrated in BAP (0 exits, 5 trims), PODD (1 exit, 4 trims), SNPS (2 exits, 2 trims), and WDAY (0 exits, 4 trims).
What to Watch
Today's October CPI release (08:30 ET) is the dominant catalyst: consensus expects headline +0.3% m/m (64% of forecasts) and core +0.2% m/m (66% at consensus, 31% at 0.3%). A core print at 0.3% or above would shift the December hike debate toward 50 bps per Waller; 0.1% could challenge the hike thesis. Fed voters Waller and Logan speak later today alongside ECB's Lane, Escriva, and Cipollone and BoE's Pill — any deviation from the hawkish script moves front-end rates. Earnings already reported yesterday include Constellation Energy, KKR, Occidental, Ferguson, Skydance, JBS, Take-Two, Rocket Lab, Credicorp, CNH, NRG, and Ascendis; today's reporters include SoftBank, Petrobras, Infineon, TransDigm, Sea, Honda, Henkel, Quanta, Vodafone, and Alcon. Key levels: Brent 91.21 (break below 90 extends risk-off), DXY 101.73 (above 102 signals dollar strength on hot CPI), gold 4,079 (below 4,050 on hawkish surprise), bitcoin 74,193 (correlated with rate expectations). Divergence: Morgan Stanley/BofA see softer CPI vs Waller's "hike regardless" stance. Open question: Will a soft core print finally force markets to reprice the December 25 bps hike probability below 50%?
