EU Close Digest - 03 Nov 2026
AI-generated close market digest from curated financial newsflow.
RBA hikes to 4.85% in split vote as US job openings hit 7.52M four-month high
US Session Open & European Close
US equities opened with a cautious rebound, the S&P 500 trading at 7,573 (+0.42%) and the Nasdaq 100 at 28,182 (+0.69%) as an AI-driven bounce offset midterm election uncertainty. European markets closed lower, the Euro Stoxx 50 at 6,151 (-0.41%), FTSE 100 at 10,653 (-1.01%) and DAX at 25,892 (-0.34%), with InvestingLive noting stocks "tumbling" as geopolitical risks and Fed policy weighed. The VIX eased to 20.59 (-2.65%), Brent slipped to $103.19 (-1.51%) on diplomatic hopes for the Iran conflict, and gold traded at $3,944 (-0.63%). The DXY edged up to 101.79 (+0.04%) while AUD/USD fell 0.3% to 0.6975 after the RBA decision. Bloomberg attributed the US advance to a revival of the artificial-intelligence trade despite voting uncertainty.
Analyst Consensus
- RBA Policy: The Reserve Bank of Australia delivered a 25bp hike to 4.85% on a 6-3 split vote, lifting the cash rate to an 18-year high. Governor Bullock offered no forward guidance, stating it is "probably good to wait for data" and acknowledging it is "not as obvious" if further hikes are needed. The RBA sees inflation above 3% until late 2027 and revised its NAIRU estimate to 4.75% with unemployment forecast at 5.1% by 2028. Three dissenters cited overtightening risks. Markets price only 35bp of additional tightening by mid-2027, implying a hike-and-hold scenario. (InvestingLive, CNBC, RBA Media Release)
- US Labor Market: Bloomberg reports US job openings surged 333,000 to 7.52 million in September, a four-month high, while layoffs dropped to the lowest level in over a year. The BLS JOLTS survey shows openings stable at 7.5 million with quits rising to 3.4 million, signaling worker confidence. Both sources agree on tight labor conditions, though Bloomberg emphasizes the unexpected jump while BLS highlights stability. The strength reinforces higher-for-longer Fed expectations, supporting the USD and pressuring rate-sensitive sectors. (Bloomberg, BLS)
- Midterm Election Positioning: Prediction markets show Democrats favored to win the House (94-95%) and Senate (78%), a sharp rise in Senate odds. CNBC flags a Democratic sweep could jolt stocks, Treasury yields, AI, energy, banks, defense and healthcare. The Financial Times notes Wall Street is positioning for policy shifts on AI and public spending. Key races in Kansas, North Carolina and Georgia will determine if Democrats achieve the net-four-seat gain needed for Senate control. Early results tonight will test the prediction-market consensus. (InvestingLive, CNBC, FT, Polymarket)
- AI Sector Rotation: Palantir shares are falling despite a Q3 beat ($2.1bn revenue, +23% YoY) because US commercial contract growth slowed to 12% YoY from 18%, prompting Morgan Stanley to cut its price target 15% and downgrade to underweight. Microsoft offered buyouts to 60,000 employees (15% of workforce) while committing $45.2bn quarterly capex, ~70% for AI. JPMorgan upgraded Microsoft to overweight on the AI spend trajectory. Marshall Wace and Millennium posted losses in October's AI rout, which Bond Vigilantes links to a broader tech selloff and bond market turbulence. (MarketWatch, Bloomberg, FT)
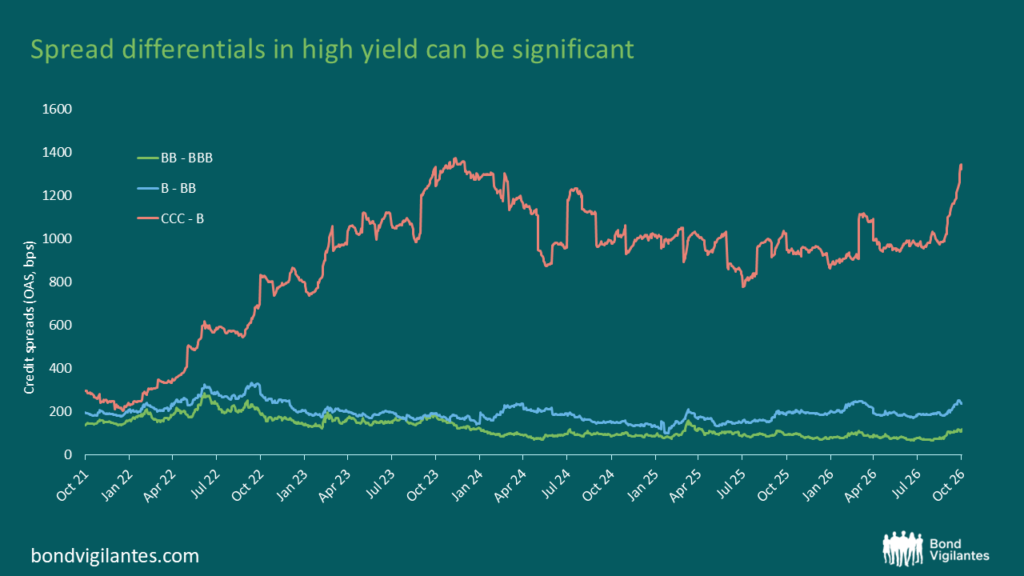
- High-Yield Gap Risk: Bond Vigilantes argues "gap risk" now eclipses traditional default risk in high yield, with bonds losing 30+ points (e.g., 98 to 65) before any default. Bloomberg OAS indices show BB-B spreads widening while BBB-BB stays flat, creating a structural chasm between BB and CCC issuers. A liquidity vacuum emerges below 85% of par where traditional investors sell but distressed buyers wait for significantly lower levels. Creditor-on-creditor violence in restructurings creates a "second gap" in recovery modeling. Rising spread dispersion favors active security selection over index-based strategies. (Bond Vigilantes)
Next Session Setup
Asia-Pacific markets will digest the RBA's split-vote hike and cautious guidance, with AUD/USD immediate support at 0.6900-15 and June lows at 0.6865-75 as downside targets per InvestingLive technicals. The US midterm results overnight will drive the next directional move; a Democratic sweep could pressure Treasury yields and rate-sensitive sectors while boosting AI and clean-energy names. The Treasury's $177bn double-bill auction (95bn 13-week, 82bn 26-week) settles 5 Nov, concentrating supply into a single session that may amplify short-end volatility. Earnings after the US close include AMD, Amgen, Arista Networks, Shopify and Booking Holdings. Saudi Arabia's fiscal deficit more than doubling on oil revenue declines (Bloomberg) and Belgium's insufficient budget cuts per the OECD add sovereign-risk context. The open question: will election confirmation of prediction-market odds trigger a relief rally, or will a Republican overperformance spark a risk-off reversal in the AI trade that has led today's bounce?
