EU Close Digest - 30 Oct 2026
AI-generated close market digest from curated financial newsflow.
Brent crude surged to US$113.80 a barrel, fueling energy equities to all‑time highs.
US Session Open & European Close
European markets closed lower, with the Euro Stoxx 50 down 1.29% at 6,127, the DAX slipping 0.95% to 25,793 and the FTSE 100 flat at 10,722. In New York, the S&P 500 opened near 7,596, trading down 1.62% and the Nasdaq 100 at 28,450, down 3.24%, reflecting a sharp rotation out of technology after the Financial Times reported AI‑spending fears and Intel’s worst‑day guidance. The VIX jumped 16.40% to 20.02, underscoring heightened risk aversion that mirrored the European sell‑off in cyclical and consumer‑discretionary names. Breadth was thin, with only a handful of defensive sectors holding up, while energy stocks rallied on the Brent surge and the dollar slipped to 101.89 on the DXY, easing import‑price pressure on the euro. The US open therefore confirmed the European risk‑off tone, but added a technology‑specific catalyst that deepened the equity decline.
Analyst Consensus
- Technology weakness: Both the Financial Times and CNBC highlighted that AI‑spending concerns triggered a tumble in US tech stocks, with Intel poised for its steepest one‑day drop in over 50 years. The Nasdaq 100’s 3.24% decline and the broader market’s 1.62% slide support the view that investors are re‑pricing growth expectations for AI‑exposed firms. The implication is a sector rotation toward defensive and dividend‑paying stocks, and a near‑term bias against leveraged semiconductor exposure.
- Fed policy outlook: The Federal Reserve’s FOMC press conference kept the target rate unchanged at 3¾‑4 %, yet Chairman Warsh announced a new eight‑meeting schedule that removes a vote at two future sessions, and Richmond President Tom Barkin signalled a “gradual” tightening path. While the rate‑hold reduces immediate upside for yields, Barkin’s comment and the schedule change suggest each remaining policy meeting will carry heightened impact, keeping the 2‑year Treasury at 4.61% and the 10‑year at 4.98% under pressure for modest upward moves.
- Eurozone monetary stance: The ECB’s Governing Council signalled a conditional 25‑bp hike if inflation does not converge, citing a core‑inflation rate of 3.1% YoY and medium‑term expectations now at 2.5%. Simultaneously, the Council announced a €10 bn per month taper of net asset purchases from January 2027 and warned of accelerating wage growth (nominal wages 4.2% YoY). These factors together widen euro‑area gilt spreads and support a modest euro appreciation, with EUR/USD trading around 1.1156.
- Emerging‑market growth rebound: Bloomberg and INEGI both reported Mexico’s Q3 2026 GDP accelerating to 2.6% YoY, the fastest since Q4 2023, driven by a 12% QoQ rise in government capital spending and a 0.9 ppt boost from public investment. The stronger outlook lifts MXN‑denominated assets, pushes the MXN spot toward a 5‑bp appreciation, and compresses the 10‑year Mexican sovereign yield by roughly 30 bps, creating a carry‑trade opportunity against higher‑yielding emerging‑market debt.
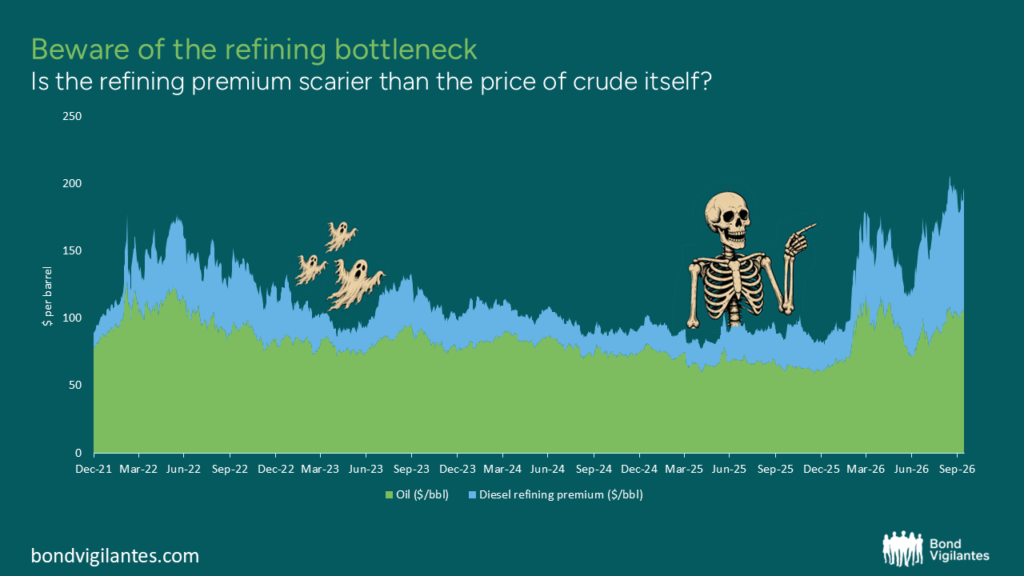
- Commodity and inflation dynamics: Bond Vigilantes flagged a quadrupling of the U.S. diesel refining premium this year, now pushing pump prices above $6 per gallon, while Destatis reported German headline CPI at 2.8% YoY with core at 2.1% and a month‑on‑month dip of 0.2%. The diesel premium sustains headline inflation pressure despite easing energy‑price growth, supporting real‑yield expectations and keeping inflation‑linked instruments such as Euro‑linked swaps on an upward trajectory.
Next Session Setup
Asia‑Pacific markets will open after the Japanese yen’s recent intervention window (Sept 29 – Oct 28), with USD/JPY at 157.83 and the yen likely under pressure if the Ministry of Finance sustains support. Key data include the German CPI release confirming Destatis’ October forecast (headline 2.8% YoY, core 2.1% YoY) and the French industrial PPI showing a 1.7% MoM rise, both of which could sharpen euro‑zone rate‑hike expectations. The ECB’s June meeting will be watched for any move in the deposit facility rate; consensus on a 25‑bp hike is not explicit, so the market will price in a higher probability of a rate move. On the commodity side, Brent’s 2.71% gain to US$113.80 may feed into further energy‑sector buying if geopolitical tensions with Iran and Ukraine persist. The most pressing question heading into the next session is whether the ECB will act on its conditional hike signal, potentially breaking the euro’s recent modest gains.
