EU Close Digest - 22 Oct 2026
AI-generated close market digest from curated financial newsflow.
Meta's $100bn wipeout on AI capex fears drags Nasdaq 100 down 2.4% as Brent hits $111
US Session Open & European Close
The S&P 500 is trading at 7,660, down 1.25% intraday, while the Nasdaq 100 has slumped 2.37% to 29,116 as Meta's forecast of "hundreds of billions" in AI spending erased more than $100bn of market value and pulled peers lower. European markets closed sharply weaker, with the Euro Stoxx 50 finishing at 6,097 (-1.78%) and the France-Germany 10-year yield spread widening to 170bps — its widest since 2011 — as French fiscal concerns drove EUR/CHF to a three-month low at 0.9200. Brent crude jumped 2.05% to $111.05 on Middle East tensions, pressuring gold to a two-month low at $4,070 (-1.93%) and triggering a flight to bonds that lifted investment-grade ETF LQD 0.73%. The VIX surged 12% to 18.70, reflecting renewed risk-off positioning. US initial jobless claims fell to a three-month low of 194,000, reinforcing the higher-for-longer rates narrative ahead of the Fed meeting.
Analyst Consensus
- AI Capex Re-rating: Meta's spending outlook triggered a sector-wide re-rating, with the FT noting markets are questioning whether massive AI capex will generate near-term returns. Nvidia CEO Jensen Huang described neocloud demand as "off the charts" but flagged scarce capital as a bottleneck, while Blackstone's Jon Gray said CoreWeave can "find a way through" financing pressure. The divergence between soaring revenue expectations and tightening funding conditions suggests further multiple compression for AI-exposed names unless earnings visibility improves.
- Oil-Driven Inflation Flight to Quality: Bloomberg reports higher oil prices from escalating Middle East hostilities revived inflation fears, pressuring gold to its lowest level in over two months and pushing global investors toward bonds. The France-Germany 10-year spread at 170bps — a 2011 high — underscores fiscal fragility in the euro area, while EUR/CHF at 0.9200 reflects euro weakness. US jobless claims at 194K (three-month low) and Canada's PPI surging 2.0% m/m (80% probability of BoC hike Oct 28 per InvestingLive) keep restrictive policy biases intact across DM central banks.
- Central Bank Divergence: The Bank of Korea held at 3.00% but signaled a possible November hike, citing 2.9% headline inflation, record exports (>$120bn), and a projected current-account surplus exceeding $450bn. Meanwhile, 83% of economists surveyed by Bloomberg expect the BOJ to hike in December — not October — with underlying inflation hitting 2% as the pivotal trigger. Turkey delivered a cautious cut as inflation slowed to a near five-year low, while the Czech Republic faces a "close call" on hiking amid energy risks. The PBOC set USD/CNY at 6.7195 (weaker than the 6.6756 estimate) and injected 173bn yuan via reverse repos, signaling managed depreciation with ample liquidity.
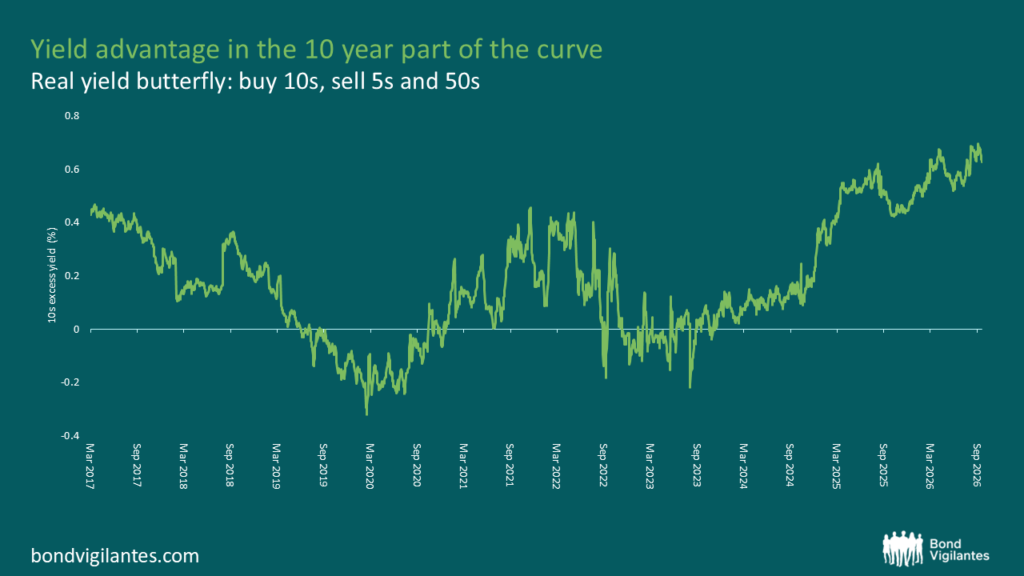
- Relative Value in Sovereign Curves: Bond Vigilantes highlights a record yield advantage of ~1.5% per annum in 10-15 year index-linked gilts versus a duration-neutral 5/50-year barbell, driven by DMO issuance distortions. The US Treasury announced $69bn 2-year, $70bn 5-year, $44bn 7-year, and $30bn 2-year FRN auctions for early November, with the 5-year as the largest nominal coupon issue. Japan's MOF conducted a liquidity enhancement auction and announced 2-year JGB issuance for November. Latam's political shift toward fiscal conservatism — 100% of 2025-26 elections won by right/center-right parties — supports sovereign and corporate bond momentum in regulated sectors. France Fiscal Stress Transmission: The France-Germany 10-year spread at 170bps (InvestingLive) and EUR/CHF at 0.9200 reflect a feedback loop where French budget uncertainty drives euro weakness, which in turn tightens financial conditions via imported inflation. Bloomberg notes Germany has zero fiscal leeway in 2027 despite marginally higher tax receipts, limiting Eurozone fiscal support capacity. With the ECB emphasizing "supportive monetary conditions given limited fiscal space in key economies," the policy mix remains asymmetric: monetary easing must offset fiscal drag, keeping euro downside risk elevated.
Tomorrow's Setup
Asia opens with the Nikkei 225 down 2.65% at 62,908 and Hang Seng off 3.03% at 22,935, setting a negative tone. The BOJ's October 30 meeting looms as the key event — no economist expects a move this month, but 83% see a December hike contingent on underlying inflation reaching 2%. Tomorrow's earnings slate includes American Express, China Shenhua Energy, Zijin Mining, Eni, SLB, and Volvo. US data flow is light; the focus stays on oil (Brent at $111.05), the France-Germany spread (170bps), and whether Meta's re-rating spreads to Microsoft, Amazon, and Alphabet ahead of their reports. The 2-year Treasury yield at 4.81% and 10-year at 5.13% (stale closes from Oct 21) will be tested by this week's $183bn in new coupon supply. The open question: does the AI capex scare mark a durable regime shift for mega-cap leadership, or do resilient earnings (PG +4% organic, Spotify subscribers +2%) provide a floor?
