EU Midday Digest - 21 Oct 2026
AI-generated midday market digest from curated financial newsflow.
French 10-year yields breach 5% for first time since 2002 as sovereign risk gauge hits 160bps
Overnight & European Session
European equities opened firmer with the Euro Stoxx 50 up 0.52% and the DAX gaining 0.50%, while the FTSE 100 was flat at -0.03%. The Nikkei 225 rose 0.85% in Tokyo trade. The euro held at 1.1230 and sterling strengthened to 1.3398 as UK CPI surprised at 3.5% y/y. Brent crude climbed to $110.94 on Middle East supply concerns. French 10-year yields surged to 5%, the highest since 2002, with the French bond risk gauge approaching 160bps — a 15-year high per Bloomberg — while German Bunds remained anchored, widening the Franco-German spread. US Treasury yields are stale from Monday's close (10Y at 5.12%), leaving the transatlantic yield gap in focus.
Key Themes Today
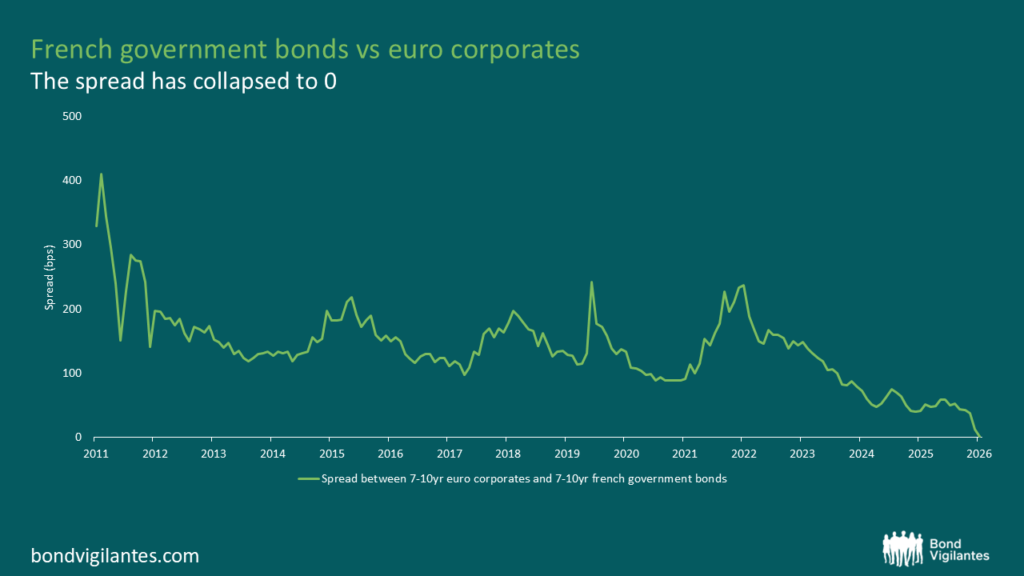
- France: French 10-year yields hit 5% for the first time since 2002, driven by fiscal deterioration and political instability concerns, according to the Financial Times and Bloomberg. The French bond risk gauge neared 160bps, a 15-year high, while Bond Vigilantes notes the spread between 7-10 year French government bonds and equivalent BBB-rated corporates has collapsed, challenging conventional risk hierarchies. French debt has risen steadily for over forty years with spikes during the GFC and COVID, per IMF data cited by Bond Vigilantes. This implies continued pressure on eurozone periphery spreads and potential spillover to regional bank balance sheets holding French sovereign paper.
- UK: September CPI rose to 3.5% y/y, the highest since October 2025, driven by an 8.2p/litre petrol price increase, per CNBC and InvestingLive. Core CPI held at 2.8% while services inflation climbed to 3.7% from 3.4%, signaling sticky underlying pressures. Markets already price a 96% probability of a 25bp BoE hike in November, with 118bps of additional tightening priced by end-2027 per InvestingLive. The autumn budget on 28 October adds fiscal uncertainty, with pound hedging costs at a five-month high per Bloomberg. This reinforces the case for further gilt yield upside, particularly at the long end.
- Japan: BOJ policymaker Himino warned underlying inflation is near the 2% target with rising medium-term expectations, arguing the bank "cannot afford to sit on its hands much longer," per InvestingLive. Market pricing assigns a 74% probability to a December hike, with a Reuters poll showing most economists expect the policy rate at 1.50% by then. Katayama added that wage-driven inflation is emerging and fiscal-monetary coordination remains intact, though board cohesion is a yen risk factor. The October 30 BOJ forecasts and subsequent board commentary are critical for JPY and JGB positioning, with further dissenting votes potentially weakening the yen.
- SpaceX/Tesla: SpaceX shares surged 10% premarket on Q3 revenue beats and Elon Musk's merger hints with Tesla, per CNBC and FT's FirstFT. CoinDesk notes the combined entity would hold over 30,000 bitcoin. MarketWatch reports SpaceX's strong results eased AI sustainability concerns, lifting US futures. However, Ken Griffin at Citadel cautions AI stocks are "in a bubble" but advises against dumping them, per MarketWatch. The divergence highlights sentiment-driven momentum versus valuation discipline: SpaceX's surge is lifting the broader AI complex despite limited merger details and no concrete earnings figures disclosed.
- Germany: Destatis reports German-Russian trade has structurally decoupled: H1 2026 imports from Russia fell 96.4% (from €15.0bn to ≈€0.5bn) while exports dropped 73.1% (from €12.7bn to €3.4bn). The asymmetry leaves German exporters with pricing power in niche sectors like high-tech machinery, while chemicals and metallurgy firms accelerate diversification from Russian inputs. The near-total import collapse reduces sanctions-related supply-chain risk and suggests permanent re-routing of commodity flows. Any uptick in the €0.5bn residual import figure would signal sanctions relaxation or compliance breaches, per Destatis.
What to Watch
Today's earnings slate includes Meta, Tesla, IBM, Texas Instruments, Lam Research, and SAP after the US close, with Thermo Fisher, Abbott, NextEra, and AT&T before the open. SpaceX already reported Tuesday after the close. The UK autumn budget on 28 October and BOJ policy meeting on 30 October (with fresh growth/inflation forecasts) are the key macro catalysts. US Treasury auctions $110bn 4-week and $105bn 8-week bills tomorrow (settlement 27 Oct), plus $75bn 17-week on 21 Oct — monitor bid-to-cover and high-yield tails for front-end absorption capacity. ECB speakers Cipollone and Lane are on the docket but full speech texts are pending. The open question: will French yields sustain above 5% and force ECB commentary on fragmentation risk, or does the BBB convergence signal a broader re-rating of sovereign risk across the G7?
