EU Close Digest - 20 Oct 2026
AI-generated close market digest from curated financial newsflow.
US pending home sales plunge 7.3% to record low, far exceeding consensus expectations of -0.5%.
US Session Open & European Close
The S&P 500 trades at 7,713, up 0.29% intraday, while the Nasdaq 100 hovers near 29,527, essentially flat, as healthcare and big-bank strength offsets lingering tech weakness. European markets closed lower, with the Euro Stoxx 50 down 0.26% to 6,129 and the FTSE 100 off 0.26% at 10,737, while the DAX was unchanged at 25,323. Brent crude slipped 1.34% to US$ 108.08 on reports of an Iranian nuclear compromise, and European natural gas retreated sharply from the €90 four-year high hit earlier as profit-taking accelerated. The VIX eased 3.4% to 17.81, reflecting reduced near-term fear despite the housing shock. The dollar index softened 0.26% to 101.71, lifting EUR/USD to 1.1233 and GBP/USD to 1.3394.
Analyst Consensus
- US Housing: The September pending home sales index collapsed 7.3% to 66.0, a 25-year low, versus a -0.5% consensus, while housing starts fell to 1.221 million against 1.305 million expected. CNBC, InvestingLive, MarketWatch and Bloomberg Economics all characterize the market as in a "deep freeze," with year-over-year pending sales down 12.6% and builder sentiment at 2012 lows. The breadth of deterioration across sales, starts, permits and sentiment suggests the downturn is structural, not transitory, and will weigh on construction, mortgage lending and consumer-spending-linked sectors well into 2027.
- Geopolitics & Commodities: Iran has reportedly agreed to secret IAEA nuclear site visits under a Qatar-Pakistan mediated framework that includes releasing US$ 6bn in frozen-fund interest, prompting a US$ 1/bbl drop in crude. Bloomberg and InvestingLive note both oil and European gas correcting on diplomatic headlines — Brent down 1.34% intraday, gas off the €90 peak — underscoring commodity markets' acute sensitivity to headline risk. If confirmed, the deal could remove a key risk premium from energy, but markets remain cautious pending official statements.
- AI Skepticism: Bloomberg highlights the dismal debut of South Korea's Elice Inc., which fell despite 400x oversubscription, and a 3.8% Kospi drop led by Samsung and SK Hynix, signaling growing doubts about AI spending sustainability. Meanwhile, CNBC reports Anthropic in talks for a second multibillion-dollar data-center deal with Nscale, suggesting demand for compute infrastructure remains robust at the project level even as public-market enthusiasm wanes. The divergence between private-capital appetite and public-equity skepticism could widen valuation gaps across the AI stack.
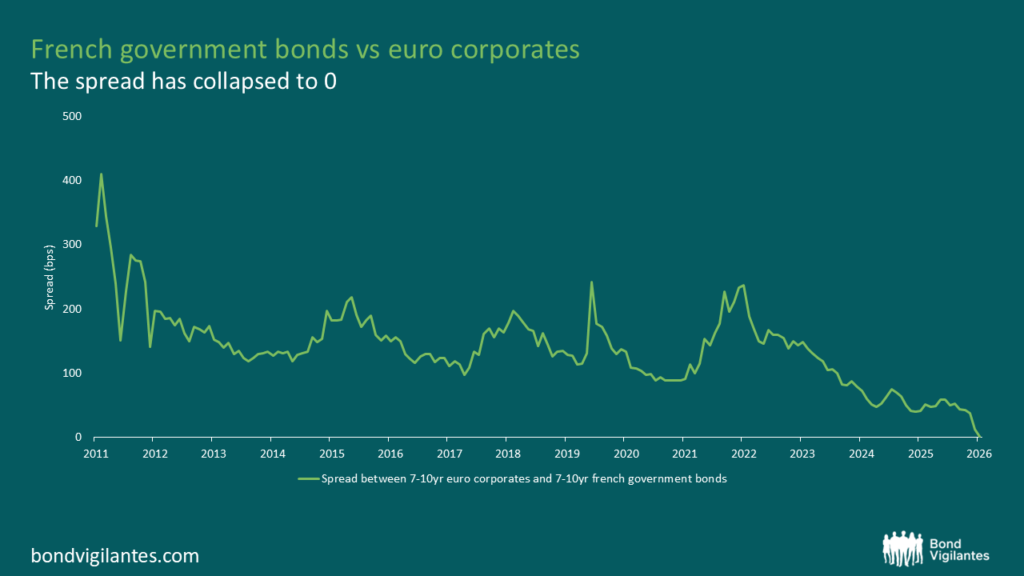
- French Sovereign Risk: Bond Vigilantes documents a historic convergence: French 7-10 year government bond yields have collapsed to match BBB-rated corporate yields, upending conventional risk hierarchies. The spread elimination, shown in M&G/Bloomberg October data, coincides with a four-decade rise in French debt/GDP and a steady deterioration in average G7 sovereign credit ratings. This mispricing implies investors are not adequately compensated for fiscal trajectory risk, potentially triggering reallocation from French paper to higher-quality corporates or core eurozone sovereigns.
- Central Bank Divergence: InvestingLive reports the BOJ may upgrade its FY2027 inflation forecast on higher oil prices but is expected to hold rates at 1.25% on October 30 (73% odds for a December hike), while the PBOC launches daily overnight reverse repos (1 trillion yuan cap, Oct 21-Nov 2) at a rate that could preview a lower policy anchor near 1.25%. Daiwa notes the BOJ's focus shifting from reaching 2% inflation to stabilizing it there, with wage durability key. The PBOC's fixed-rate tender structure and post-November continuation will clarify whether China is easing meaningfully or merely managing month-end liquidity.
Tomorrow's Setup
Asia opens with the Nikkei down 1.3% at 64,075 and Hang Seng off 1.32% at 23,868, setting a cautious tone. The BOJ's October 30 meeting looms as the key event: markets price no hike next week but 73% odds for December, and any inflation-forecast upgrade could pull forward tightening expectations. In the US, the earnings slate is heavy — Meta, Tesla, SAP, Texas Instruments, IBM, Thermo Fisher, Abbott and Lam Research all report Wednesday — with GM's guidance cut and truck-production pause today underscoring auto-sector fragility. Treasury auctions continue with US$ 105bn of 8-week and US$ 110bn of 4-week bills on October 22 (settlement Oct 27); bid-to-cover and high-yield metrics will test short-end demand after the 13-week's US$ 95bn offering. The open question: whether the housing data's magnitude forces a reassessment of the Fed's "higher for longer" stance, or if the Iran de-escalation and resilient services hiring (Amazon +300k seasonal) keep the soft-landing narrative intact.
