EU Close Digest - 08 Oct 2026
AI-generated close market digest from curated financial newsflow.
Brent crude surges 5.3% to $105.51 on Strait of Hormuz tanker attacks, lifting yields and pressuring equities globally.
US Session Open & European Close
European markets closed sharply lower, with the Euro Stoxx 50 down 0.76% at 6,134, the DAX shedding 1.12% to 24,824, and the FTSE 100 slipping 0.15% to 10,443 as the French bond sell-off and oil spike dominated sentiment. The US open confirmed the risk-off tone: the S&P 500 is trading at 7,772 (-0.38%) and the Nasdaq 100 at 30,970 (-0.61%), while the 10-year Treasury yield climbed to 5.31% (+3bp intraday) and the VIX rose 3.18% to 15.56. Brent crude jumped 5.30% to $105.51 on tanker attacks and slowing flows through the Strait of Hormuz, per the Financial Times, overriding last month's recovery to near 90% of prewar transit levels. The dollar edged higher with DXY at 102.27 (+0.03%) and EUR/USD at 1.1201 (-0.47%), while gold held near $4,140. Energy stocks outperformed on the oil surge, but rate-sensitive sectors lagged as the strong jobless claims print (197K vs 200K expected) reinforced Fed tightening expectations.
Analyst Consensus
- Energy & Geopolitics: Oil prices jumped 5.3% to $105.51 per barrel on tanker attacks and slowing flows through the Strait of Hormuz, per the Financial Times, reversing last month's recovery to 90% of prewar transit levels. The supply disruption fear overrides demand concerns, lifting energy equities while pressuring inflation expectations and sovereign yields. Higher oil could complicate central bank easing cycles, particularly for the ECB and Fed, as noted in the FT's market wrap. Investors should monitor Hormuz transit data and inventory reports for confirmation of sustained tightness.
- Labor Market & Fed Policy: US initial jobless claims came in at 197K versus 200K expected, reinforcing a historically tight labor market that gives the Federal Reserve room to hike further, according to InvestingLive. Continuing claims edged up to 1.716M, suggesting some frictional unemployment but not enough to offset the low-layoff narrative. The data triggered a risk-off move: the Dow fell 400 points, the Nasdaq 100 dropped 241 points, and the 10-year yield rose to 5.324%. CNBC's Fed survey shows 1-year inflation expectations at 3.9%, the highest since May 2023, supporting a higher-for-longer rates view.
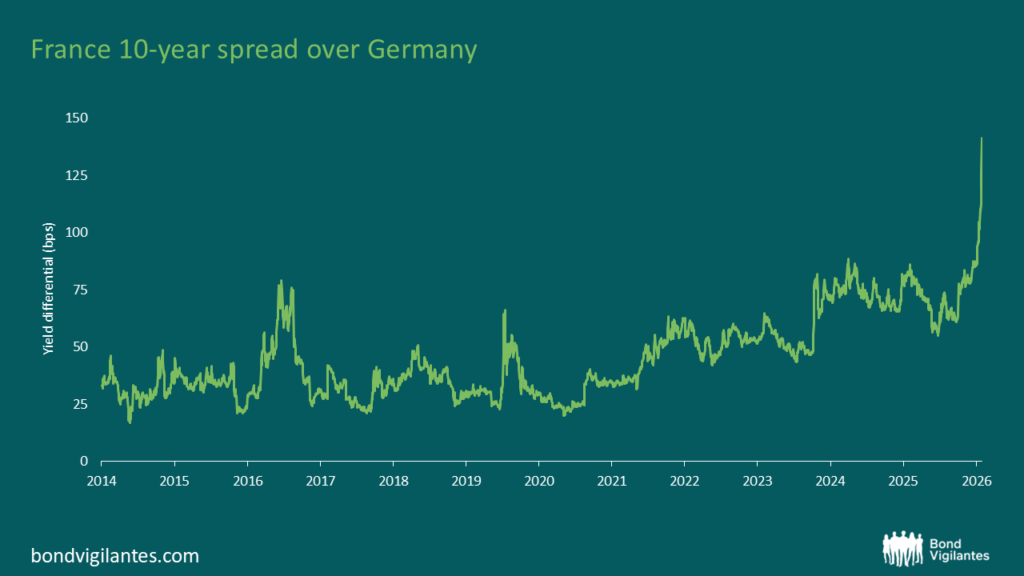
- European Sovereign Risk: French bond spreads at 150bps over Bunds may understate fiscal risk, with Bond Vigilantes noting Italian spreads exceeded 500bps during the sovereign crisis. Asset managers cited by the FT argue fears of a Eurozone blow-up are overdone, prompting bottom-fishing, but the ECB's Transmission Protection Instrument requires credible fiscal adjustment—complicated by France's presidential election and Germany's reduced backstop willingness. The piece suggests shorting Spanish bonds against duration-matched Bunds as a cheaper hedge, given Spain's 100% debt-to-GDP ratio and snap election.
- UK Fiscal-Monetary Tension: BOE Governor Bailey warned fiscal policy's countercyclical effectiveness is diminishing due to low growth and frequent shocks, per Bloomberg and InvestingLive. He noted 10-year gilts rose 4bps to 5.49%, markets volatile but not illiquid, and greater government debt absorption has increased fragility. BOE policymaker Greene sees second-round inflation risks from wage growth around 3.5% next year, voted for a 25bps hike in September, with markets pricing 84% probability of a November hike. This tightens the UK policy outlook despite growth concerns.
- China Trade Resilience: The WTO lifted its goods trade outlook as AI-related demand outweighs war strains, per Bloomberg Economics, though no specific growth numbers were provided. China's 10-year yield touched 1.7%, bucking the global bond rout, per the Source Radar. South Africa's largest trading partner for manufactured goods shifted to China from the euro area, per the SARB. This suggests Asian supply chains and tech-driven trade may decouple from Western cyclical weakness, supporting EM exporters and commodity currencies.
Tomorrow's Setup
Asian markets face a negative handover with the Nikkei closing -1.42% at 69,042 and the Hang Seng -1.43% at 23,786; watch for further reaction to the oil spike and US yield surge at the open. Key macro releases tomorrow include Delta Air Lines (DAL) and Tryg (TRYG.CO) earnings, while PepsiCo (PEP) has already reported before today's US open. Polymarket pricing shows 99% probability US unemployment won't reach 6% in 2026 and 90% odds against a 0.4% monthly inflation increase in September. Critical levels to monitor: Brent above $105, the US 10-year above 5.30%, and S&P 500 support near 7,750. ECB and Fed speakers are scheduled through the European session. The central question: whether the oil supply shock translates into sustained inflation pressure forcing central banks to resume tightening, or if demand destruction from higher rates caps the rally.
